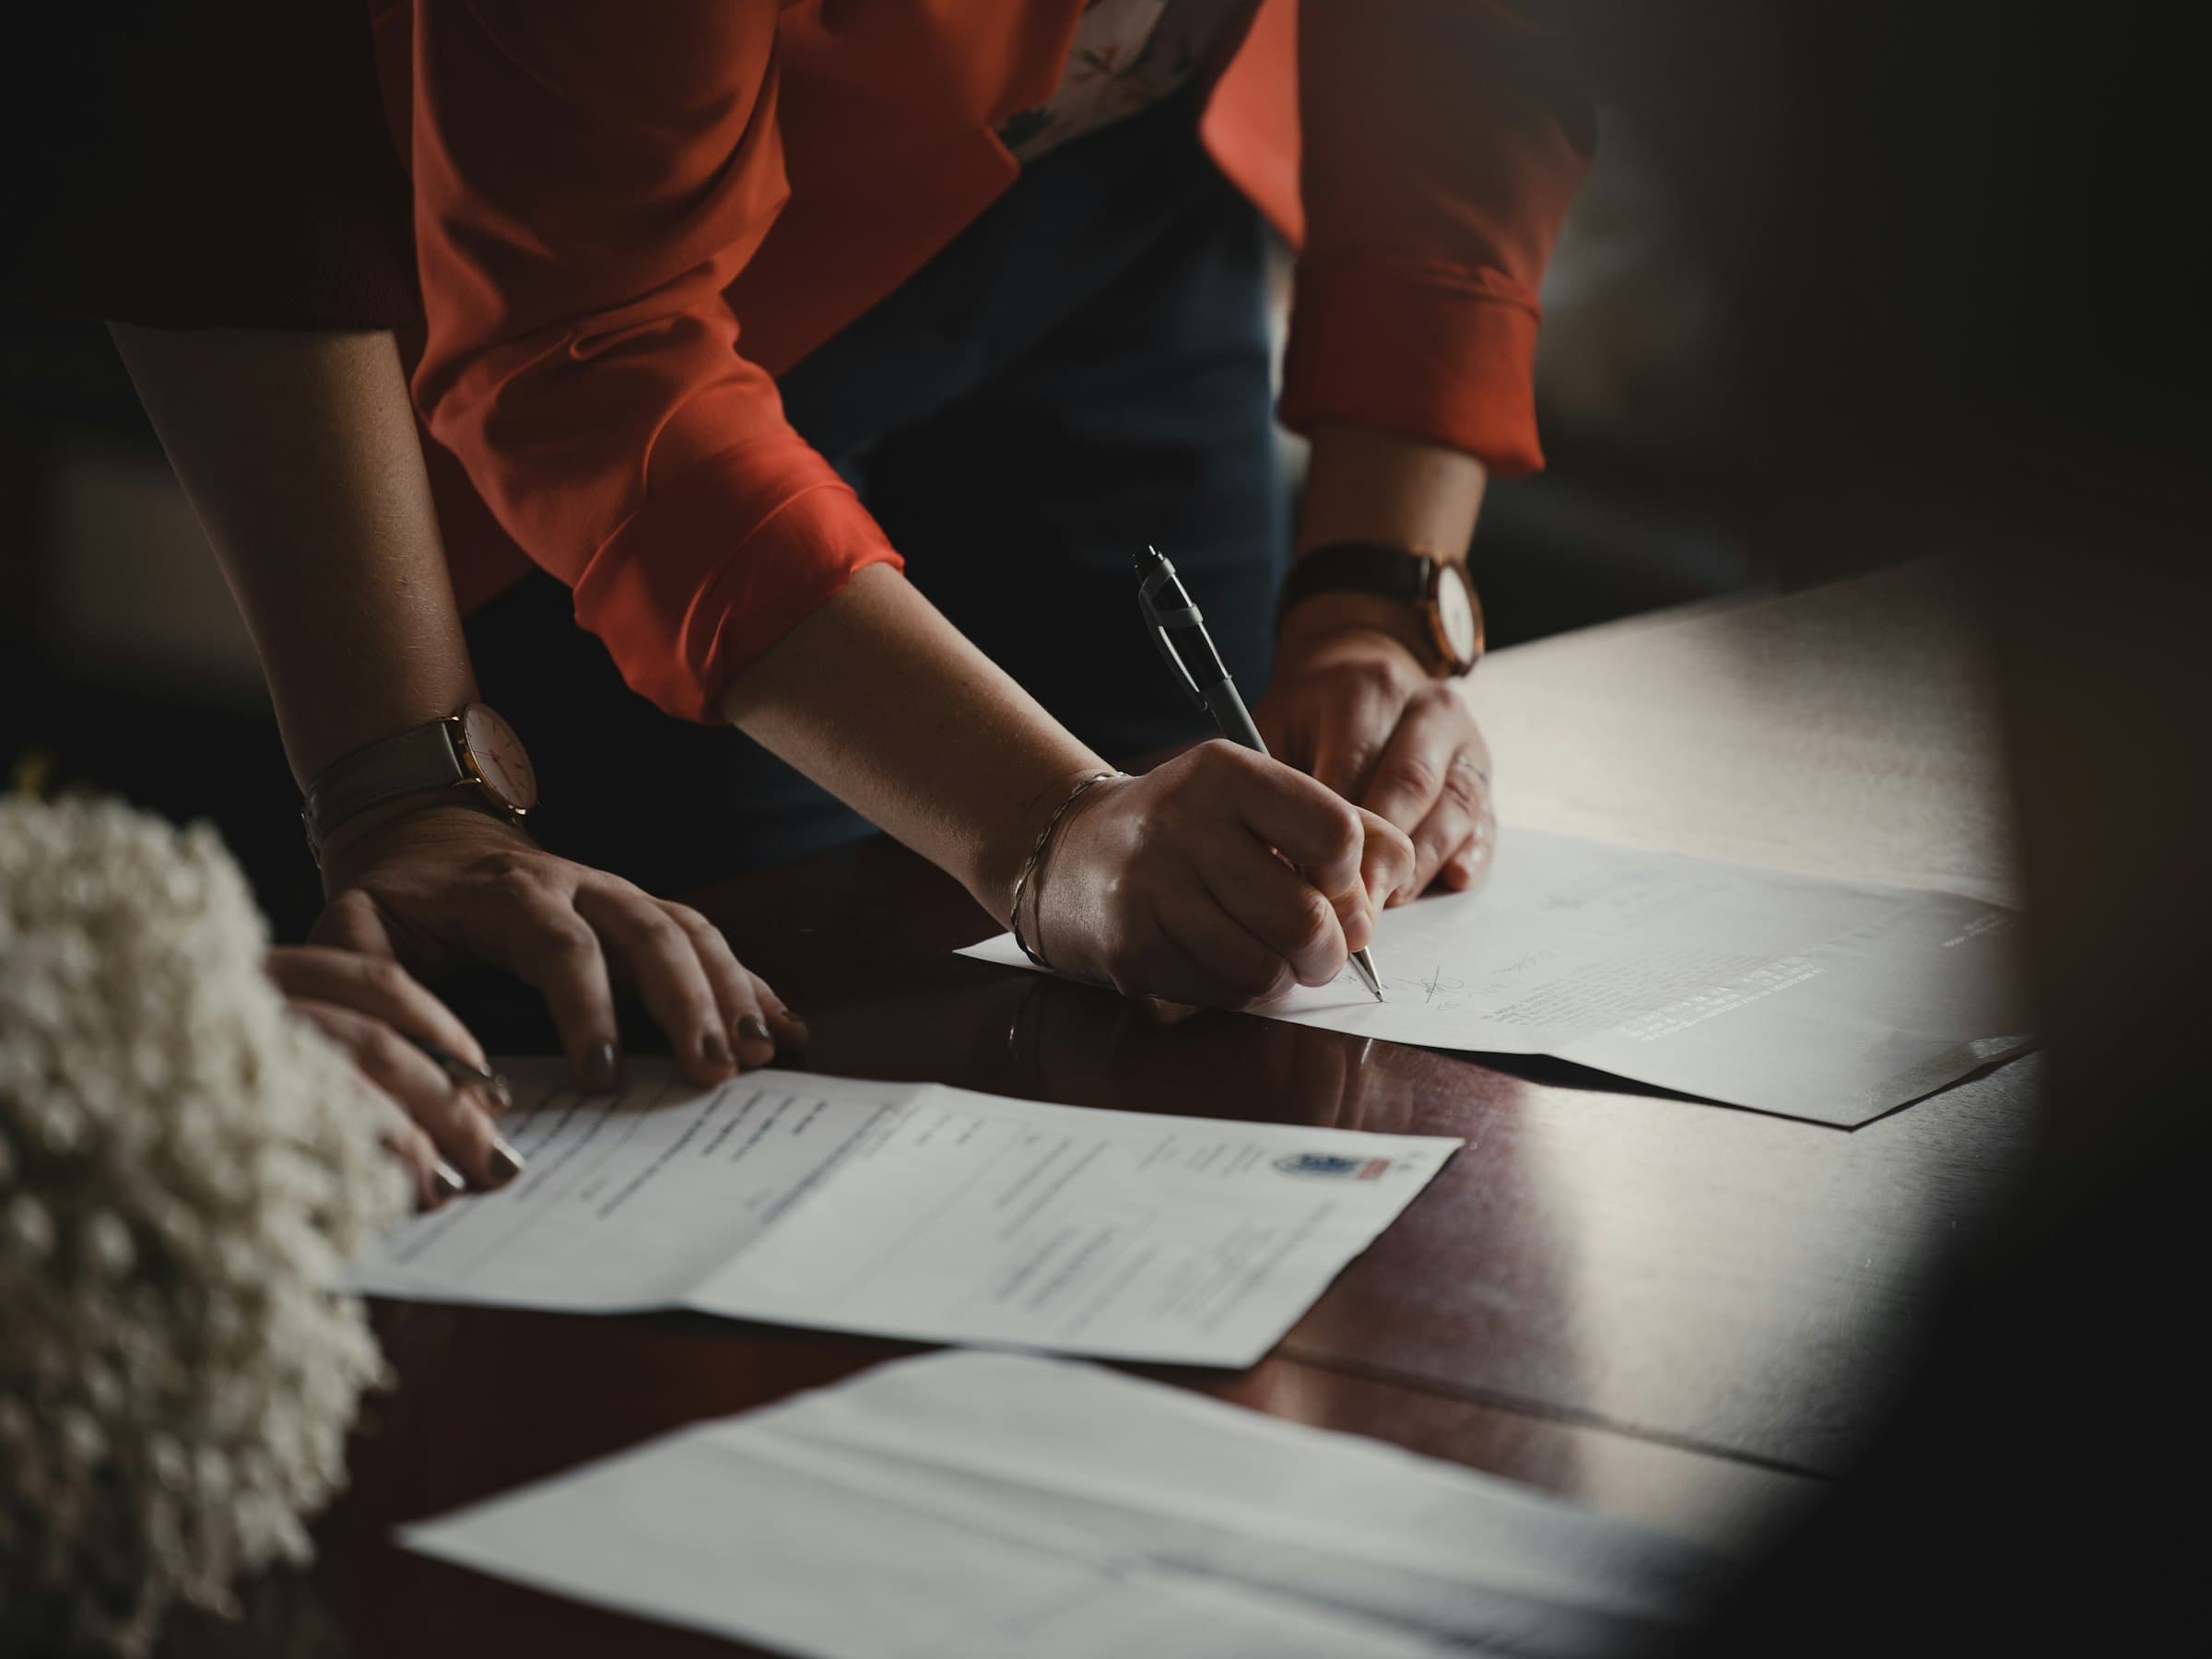
For a family-owned business, an IPO is often the first time outside shareholders, independent directors and a regulator look closely at how it is run. SEBI compliance then becomes part of ordinary management, with disclosure, governance and trading rules that apply from the day the shares list. Putting the corporate record, related-party dealings and board processes in order before filing makes both the issue and the years after it easier.
SME IPOs and other public issues
Public issues are governed by the SEBI (Issue of Capital and Disclosure Requirements) Regulations, 2018, together with the prospectus provisions of the Companies Act, 2013. For a main-board IPO the draft red herring prospectus is filed with SEBI for its observations. Smaller issuers can list on the SME platforms, BSE SME and NSE Emerge, under Chapter IX of the Regulations: an issuer with post-issue paid-up capital of up to ₹10 crore must use that route, and one with up to ₹25 crore may choose it.
An SME IPO differs in process as well as size. The draft offer document is examined by the exchange, and SEBI does not issue observations on it; the issue must be fully underwritten, and market making is compulsory for three years from listing. SEBI tightened the SME framework in 2025 with a minimum operating-profit record and limits on the offer for sale and on the use of proceeds, so eligibility should be tested early. Our issue work covers:
- eligibility review and clean-up of the corporate record before filing
- due diligence and drafting of the offer document with the lead manager
- promoter lock-in, identification of the promoter group and related-party disclosures
- rights issues, preferential allotments and qualified institutions placements
- private placements under Section 42 of the Companies Act, 2013
- listing of non-convertible debentures and other debt securities
Listing obligations after the IPO
The SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015 govern a listed company's continuing duties. Under Regulation 30, board decisions must be disclosed within thirty minutes of the meeting closing, and other material events within twelve or twenty-four hours depending on whether they arise within the company. Related-party transactions need audit committee approval, and material ones need prior shareholder approval under Regulation 23.
Results, shareholding patterns and corporate governance reports are filed on fixed timelines, and the exchanges impose fines for delay. We review disclosure policies and board processes, and help companies decide whether a development is material.
Takeovers, insider trading and SEBI proceedings
The SEBI (Substantial Acquisition of Shares and Takeovers) Regulations, 2011 require an open offer for at least 26% of the shares when an acquirer reaches 25% of the voting rights, acquires more than 5% in a financial year after holding 25%, or acquires control. Holdings of 5% and every later change of 2% must be disclosed. Acquisitions of listed companies are planned with our M&A practice.
The SEBI (Prohibition of Insider Trading) Regulations, 2015 prohibit trading while in possession of unpublished price sensitive information. Listed companies need a code of conduct, a structured digital database of those with access to such information, trading window closures and pre-clearance for designated persons, and insiders can use trading plans for trades scheduled in advance.
SEBI enforces these rules through inspections, show cause notices, adjudication and directions under Sections 11 and 11B of the SEBI Act, 1992, and many proceedings can be settled under its Settlement Proceedings Regulations, 2018. Appeals lie to the Securities Appellate Tribunal in Mumbai, and shareholder disputes may reach the NCLT; our civil and commercial litigation practice handles both.
Issuers and listed companies can reach the Raipur office by phone or email.
What the practice handles
- Main-board and SME IPOs, from eligibility review to listing
- Rights issues, preferential allotments and qualified institutions placements
- Private placements and listed non-convertible debentures
- LODR compliance reviews, disclosure policies and materiality assessments
- Related-party transaction policies and approvals
- Open offers, takeover exemptions and disclosures under the takeover regulations
- Insider trading codes, structured digital databases and trading plans
- Replies to SEBI and exchange notices, settlement applications and appeals to the SAT
- Shareholder disputes, including oppression, mismanagement and class action petitions
Where these matters are heard
- Securities and Exchange Board of India
- BSE and NSE, including the BSE SME and NSE Emerge platforms
- Securities Appellate Tribunal, Mumbai, with a further appeal to the Supreme Court
- National Company Law Tribunal, for oppression, mismanagement and class action petitions
Questions about Capital Markets & Securities
How is an SME IPO different from a main-board IPO?
The SME route is for smaller issuers: it is compulsory where post-issue paid-up capital is up to ₹10 crore and optional up to ₹25 crore. The exchange examines the offer document instead of SEBI, the issue must be fully underwritten, and a market maker must provide liquidity for three years. A company listed on an SME platform can later migrate to the main board if it meets the conditions.
When must a listed company disclose a material event?
Under Regulation 30 of the LODR Regulations, decisions taken at a board meeting must be disclosed within thirty minutes of the meeting closing. Events arising within the company must be disclosed within twelve hours, and other events within twenty-four hours. Some events, such as mergers and changes in directors, are material by definition; others are judged against the thresholds in the regulation and the company's own policy.
What triggers an open offer?
An acquirer must announce an open offer on acquiring 25% or more of the voting rights in a listed company, on acquiring more than 5% in a financial year once it already holds 25% or more, or on acquiring control, directly or indirectly. The offer must be for at least 26% of the total shares. Regulation 10 sets out exemptions, such as certain transfers among promoters.
Who counts as an insider under SEBI's regulations?
An insider is a connected person, or anyone in possession of or with access to unpublished price sensitive information. Connected persons include directors, employees and others whose position or relationship with the company gives them such access, and immediate relatives are presumed to be connected. Insiders may not trade on the information or pass it on, except for legitimate purposes or to meet legal obligations.
Where are SEBI orders challenged?
An order of SEBI or its adjudicating officer can be challenged before the Securities Appellate Tribunal within forty-five days of receiving it, and the Tribunal may admit a later appeal for sufficient cause. A further appeal lies to the Supreme Court on a question of law within sixty days of the Tribunal's order. Many matters are resolved earlier through SEBI's settlement process.
A question that is not answered here? Send it to the firm.
This page describes the law in general terms as of 24 September 2026. It is not legal advice. The outcome of any matter depends on its facts, and the firm does not guarantee results.